Signing Away the Safety Net: Personal Guarantees for UK Directors in 2026
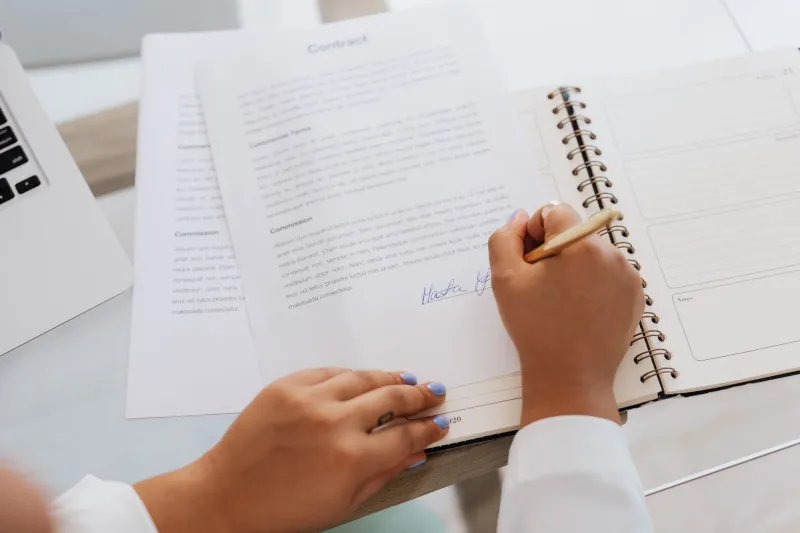
Limited liability is one of the better-known features of the UK company structure, but it is not unconditional. When a bank, landlord, invoice financier or trade supplier asks for a personal guarantee, the director is being invited to step outside the corporate shield and stand behind the company’s obligations with their own assets. In 2026, with credit conditions still selective and insolvency numbers elevated in several sectors, these requests are routine. The risk is not the signature itself; it is the scope of the document behind it.
A separate contract, not a formality
A personal guarantee is a distinct legal agreement between the guarantor and the beneficiary. It sits alongside the company’s lease, loan or supply terms but is not diluted by them. Many guarantees are drafted on the lender’s standard terms, are described as continuing, and are payable on demand. The director may believe they are guaranteeing a specific facility or a single property, only to find that the wording captures a revolving credit line, future variations and associated costs.
A guarantee should not be confused with an indemnity, although the two often appear together. A guarantee is a promise to meet the company’s liability if the company fails to do so. An indemnity is a primary obligation to make good a loss, which can be broader. The distinction matters when disputes arise, because the defences available to a guarantor are narrower under an indemnity.
The long reach of the all-monies clause
An all-monies clause is the provision that converts a guarantee from a defined commitment into an open-ended one. It typically covers all present and future obligations owed by the company to the beneficiary, including principal, interest, fees, enforcement costs and liabilities arising from variations or renewals of the underlying arrangements. For a commercial lease, it may survive a rent review or a change in the tenant’s group structure. For invoice finance, it can capture a fluctuating ledger. For supplier credit, it may apply to every order placed under a running account.
The practical danger is that the director’s exposure can grow without a fresh signature. If the company refinances at a higher level, extends its overdraft or enters a new contract under the same master agreement, the guarantee may follow automatically. Before signing, the director should ask for the full suite of documents, not only the one-page guarantee form, and should trace how the all-monies wording interacts with the underlying facility.
Negotiating the perimeter: caps, carve-outs and clocks
A guarantee is a negotiated instrument, even when it arrives as a standard form. Lenders and landlords have risk departments, but they also have commercial incentives to complete transactions. The director’s goal is to define the perimeter of personal exposure rather than accept an unlimited promise.
A financial cap is the most effective control. This should be a fixed sterling amount that includes all interest, costs and enforcement expenses, not a cap on principal alone. A guarantee expressed as a percentage of the facility can also work, provided the percentage is calculated at the point of demand and is not subject to later adjustment. Where a cap is not available, a time limit is the next best protection: liability expires after a defined period, such as twenty-four months from the date of termination of the underlying agreement, or is reviewed annually.
Carve-outs should be specific. The director may seek to exclude liabilities arising from future variations that were not consented to, obligations relating to a different group company, or amounts resulting from the beneficiary’s own negligence. A release mechanism is valuable: the guarantee falls away if the company meets a defined covenant, such as a debt-service ratio, for two consecutive quarters. If the guarantee is joint and several with other directors, the director should understand that each guarantor may be pursued for the whole debt, not merely their share, and should consider a contribution agreement between the guarantors.
Demand, limitation and the joint-and-several trap
Most personal guarantees are payable on demand. A demand letter is not a court judgment, but it is a formal step that can lead to bankruptcy proceedings or a claim against the guarantor’s home. The director should check whether the demand complies with the guarantee’s notice provisions and whether the underlying debt is genuinely due. Limitation periods matter: in England and Wales, a simple contract claim is generally subject to a six-year limitation period, while a guarantee executed as a deed may attract twelve years. The date from which time runs can be complex, particularly with continuing guarantees.
Joint and several liability means the beneficiary can choose which guarantor to pursue, and there is no obligation to pursue the company first unless the guarantee says so. A director who has signed alongside others should not assume that the lender will divide the claim equally. Contribution rights may exist between guarantors, but they are only as useful as the other guarantors’ ability to pay.
If a guarantee is called in: the realistic options
The worst response is silence. A director who receives a demand should immediately request a full statement of the guaranteed debt, including principal, interest and costs, and should check the guarantee’s execution, any expiry date and whether the beneficiary has varied the underlying agreement without consent. A variation that is materially prejudicial to the guarantor can, in some circumstances, release the guarantee, but this is fact-specific and requires legal advice.
Negotiation is often more productive than litigation. The beneficiary may accept a discounted lump sum, a staged payment plan or a release in exchange for a charge over specific assets. If the company is still trading, a refinancing or a company voluntary arrangement may reduce the pressure. Personal insolvency options, including an individual voluntary arrangement or bankruptcy, should be treated as last resorts, but they are legitimate tools where the exposure is unmanageable. Early communication generally produces better outcomes than waiting for a statutory demand.
Keeping the guarantee file alive
A personal guarantee is not a document to file and forget. Directors should maintain a register of every guarantee signed, the beneficiary, the cap, the expiry date and the underlying obligation. Reviews should take place annually and whenever a facility is renewed or a lease is assigned. Board minutes should record the decision to sign and the commercial rationale. If a guarantee is released, the release should be obtained in writing. In 2026, with lenders alert to covenant breaches and landlords focused on rent collection, the director who understands the perimeter of their personal exposure is better placed to protect both the company and their own financial position.
This article provides general guidance and is not a substitute for legal advice on a specific guarantee.